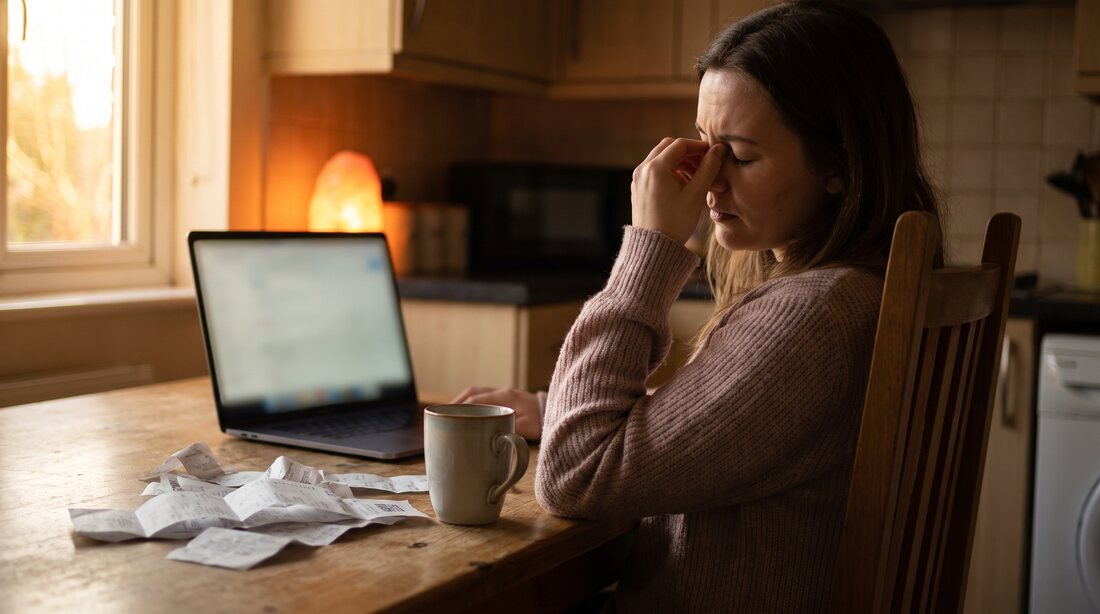
Most abandoned budgets aren't abandoned because the maths went wrong. They're abandoned because logging a $4 coffee meant opening a laptop. That's the real budget spreadsheet vs app question, and it has almost nothing to do with features. A spreadsheet asks you to sit down. Spending doesn't happen sitting down.
I've watched people build beautiful sheets. Conditional formatting, a little chart that turns red when dining out goes over. Three weeks later the last row is dated the 9th. The template wasn't the problem. The gap between spending the money and recording it was.
What a budget spreadsheet is genuinely good at
I don't think spreadsheets are the enemy, and anyone telling you to ditch yours immediately is selling something. If you want a column that splits rent three ways and subtracts your flatmate's half of the internet bill, no app is going to beat a formula you wrote yourself. They're free, and nobody is ever going to sunset them.
Sheets are also the honest choice for anything unusual. Freelance income arriving in lumps, or a sinking fund for a car repair eleven months out. Apps make opinionated guesses about how normal people budget. A spreadsheet makes no guesses at all, which is exactly what you want when your situation isn't normal.
And they're private in the most literal sense. A file on your own machine, no account, no company that could get acquired next year. That matters more to some people than any feature, and it's a fair thing to weigh.
Why spreadsheets quietly stop getting updated
The catch is the gap between the spend and the entry. Anything longer than a few seconds and you start saving it for later. Later becomes Sunday. Sunday becomes a pile of forgotten receipts, and then the sheet is wrong. A wrong sheet is worse than no sheet, because you make decisions off it while believing it.
There's a second failure that's less obvious. Catching up on a week of spending in one sitting means reconstructing it from memory, and memory flatters. The cash ones vanish first, then the small card taps. What you end up with is a tidy record of your big, defensible purchases and a blind spot where the actual leak was.
A budget you update once a week isn't tracking your spending. It's recalling it, and recall is generous.
What an expense tracking app buys you
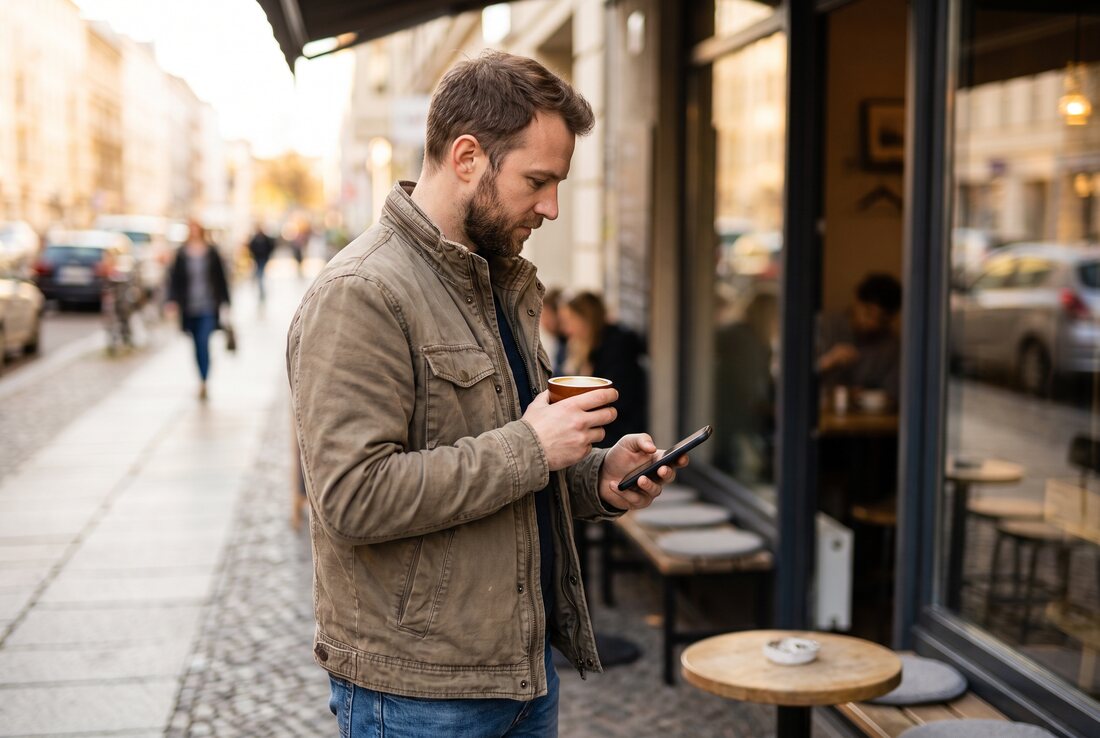
Speed, basically. Bud logs an expense in about seven seconds, and you can start one straight from the iPhone Action Button without hunting for the icon on a home screen. That's the whole trick. Log it while you're still standing at the counter and the pile never forms.
Everything else follows from that. Once the entries are actually happening in real time, the numbers are true, and a budget with true numbers starts being useful instead of decorative.
- No bank login. Same privacy stance as your own sheet. Bud never asks you to connect an account, so there's no third party holding your banking credentials.
- Your data stays on your iPhone. With iCloud sync only if you switch it on. It isn't sitting on a company server by default.
- Buddy sorts it. The categorising you'd do by hand in a spreadsheet happens on its own, and you can ask Buddy questions about your spending in plain English instead of writing a formula.
- Splitting is built in. Shared dinners and group trips land in the same place as everything else, so your half of the bill is part of your actual budget rather than a separate tab you forget.
- Splitwise import. If you've already got shared history there, it comes with you.
What each one actually costs
A spreadsheet costs nothing, ever. That's a real point in its favour and I'm not going to talk you out of it. Bud is free to download, and Bud Plus is $1.99 a month or $15.99 a year if you want the extras. So the honest framing is: the app costs about the price of one coffee a month, and the spreadsheet costs you a few minutes every day you remember to open it.
The other cost is the one people skip. Building and maintaining a good sheet is a hobby. Some people love it, and if you're one of them the maintenance isn't a cost at all. If you don't love it, you're paying in willpower, and willpower runs out faster than $15.99 a year does.
Bud is iPhone only. If you're on Android, or you want the same budget open on a laptop at work, a spreadsheet in a shared drive is still the more practical answer, and that's worth saying plainly.
How to decide, honestly
Go and look at your sheet right now. Find the date on the last row. That single number tells you more than any comparison table, this one included.
- Updated in the last day or two? Your system works. Keep it. Nothing here is worth breaking a habit that's already running.
- Last row is a week or more old? You've already answered the question. The fix isn't a better template, it's a shorter path between spending and logging.
- You've never made it past a month? Try the app for one month and don't build anything. If it doesn't stick either, at least you've learned the problem isn't the tool.
You can also run both, and plenty of people do. Track day-to-day spending on your phone where the friction is lowest, then keep a spreadsheet for the annual view and the tax paperwork. They're not really competing for the same job. One is a notebook you carry, the other is a filing cabinet.
If you've quietly stopped opening the sheet, though, the honest read is that you didn't fail at budgeting. You just picked a tool that needed you to be at a desk, and your money doesn't wait for that.
Track your money in seconds, not spreadsheets.
Bud is free to download, built for iPhone, and never asks for a bank login.
